

Expense IQ Money Manager analysis by Appwee
I approached Expense IQ Money Manager as I would any finance app I might recommend to a friend: not just by checking whether it can record spending, but by asking how comfortable it feels to use every day. Money tools handle information that can reveal a lot about a person’s routines, so convenience matters, but so do visible choices, account controls, and the way carefully a user can decide what to enter.
Expense IQ is a free finance app from Handy Apps, designed around spending records, budgets, and bill reminders. It has been available since May 14, 2014, and its current version is 2.3.2. The app has passed one million installs, with a 3.2 average from roughly twenty-three thousand ratings and about two thousand eight hundred written reviews. Those figures suggest a well-known tool with a mixed reception rather than an automatic recommendation.
My overall impression is that it works best for someone who wants a practical manual money journal with several planning tools in one place. It is less convincing for people who expect a polished banking companion, automatic account synchronization, or a highly guided financial coaching experience. The important distinction is that Expense IQ gives you a workspace for organizing money; it does not replace the judgment required to keep that workspace accurate.
How Expense IQ earns trust in everyday money tracking
A useful starting point for people who want to stay in control
The strongest trust signal in a personal finance app is often simple: can I understand what I am recording, correct mistakes, and decide how much detail to keep? Expense IQ’s central approach is familiar and approachable. You enter expenses, arrange them into a personal picture of your spending, plan budgets, and use bill reminders to avoid relying entirely on memory.
That model suits people who do not want their financial life reduced to a stream of unexplained transactions. Manual entry takes effort, but it also creates a deliberate pause. When I record a coffee, a transport fare, or a household purchase myself, I am more likely to notice patterns than when an automated feed silently categorizes everything in the background.
There is a trade-off, of course. A manual tracker is only as useful as the consistency of the person using it. Missed entries can make a budget look healthier than it really is, while incorrect categories can distort the picture. I would not treat the app as a passive source of truth. I would treat it as a personal record that needs occasional checking.
The free price makes that experiment easy. You can try the basic workflow without committing money at the start, while in-app purchases range from $3.49 to $124.99 per item. That wide range is a reason to inspect each purchase screen carefully before paying. A free download is helpful, but it should not be confused with every useful capability being permanently free.
What the app is good at when your finances are uncomplicated
Expense IQ makes the most sense for a person managing ordinary household spending, a student tracking a limited allowance, or a couple who wants a shared routine for bills and discretionary purchases. It can also be useful for someone trying to understand where money disappears each month without immediately moving to a complicated spreadsheet.
A realistic example would be a worker paid monthly who records rent, groceries, fuel, subscriptions, and occasional leisure spending. At the start of the month, that person can create a simple plan for recurring obligations and leave room for flexible categories. During the week, they can enter purchases close to the moment they happen. Before the next payday, the record becomes a basis for deciding whether the problem was overspending, irregular bills, or simply forgetting several small transactions.
That workflow is more valuable than it sounds because small expenses are easy to dismiss individually. A budget planner can expose the combined effect, while a bill reminder can separate predictable commitments from optional spending. The app is therefore not only a ledger. Used consistently, it becomes a prompt to make decisions before the money is gone.
Controls deserve attention before you enter sensitive details
Because this is a money-management app, I would not rush through setup. I would first look at the permissions requested by the installed version, read the app’s current privacy and data-handling explanations, and decide whether the requested access matches what I actually want to use. I would also check whether the store page and the app itself clearly explain account, backup, export, or deletion choices before building a long financial history.
I cannot responsibly turn the app’s category into a guarantee about privacy. A finance label does not automatically prove that information stays only on the device, nor does it tell me how every optional service handles data. The sensible approach is to verify the visible choices in the version you install. If a feature asks for access that is unnecessary for your preferred workflow, I would leave it disabled where the system allows that.
The same caution applies to account controls. Before depending on reminders or historical records, I would identify how the app protects access, whether a passcode or device security option is available, and what happens if the phone is replaced. These are not glamorous questions, but they matter more than colorful charts when the app contains months of spending history.
My practical rule is to test the control path before trusting the record. Add a few harmless sample entries, edit one, remove another, and inspect the settings that govern notifications and storage. This short trial tells you more about the app’s transparency than simply opening the dashboard and admiring the totals.
Where sensitive moments appear in normal use
The first sensitive moment is data entry itself. A detailed transaction can reveal not only the amount spent but also where you were, what you bought, and how often you return there. I would avoid placing unnecessary personal notes in descriptions. A category and amount may be enough for a budget, while a highly specific note could create extra exposure without adding useful insight.
The second moment is a shared phone or shared household. Someone who can open the app may see spending patterns that were never intended for casual viewing. If you share a device, check the available locking and notification settings, and be careful with reminder text that might appear on the lock screen. A bill alert is useful only if it does not disclose more than you are comfortable displaying.
The third moment is moving or restoring information. Before switching phones, resetting a device, or uninstalling the app, I would confirm how records can be preserved and whether the process is understandable. I would not assume that a finance app automatically provides a complete recovery path simply because it stores a history. If the app offers an export or backup route in your version, test it with a small sample first and keep the result somewhere you control.
These checks are especially important for people who use the app for tax-related notes, reimbursement records, or business expenses. Expense IQ may be convenient for organizing those entries, but I would not make it the only copy of documents or information needed for formal reporting. A personal tracker is not the same thing as an accounting archive.
How to build a reliable routine instead of a neglected ledger
The best way to use Expense IQ is to make recording friction predictable. I would choose a small set of categories that reflect actual decisions rather than creating a separate label for every shop. “Groceries,” “eating out,” and “household” may be more useful than a long list that becomes tiring to maintain. The goal is to make the next month easier to compare with the last one.
A less obvious but valuable habit is to review uncategorized or questionable entries before changing the budget. If a purchase is assigned incorrectly, the app can make a behavioral problem look like a category problem. For example, moving frequent restaurant spending into groceries may make the grocery budget appear too high while hiding the real choice that needs attention.
I would also set reminders around the moment bills actually need action, not merely around their due dates. If a payment requires transferring money or checking an account, an earlier prompt is more useful than a last-minute alert. At the same time, too many notifications can train you to dismiss all of them. Keep only reminders that lead to a clear action.
Another useful workflow is a weekly reconciliation. Compare recent entries with receipts, card notifications, or your bank statement, then correct errors while they are still easy to remember. This does not require constant monitoring. A short, regular review is usually more sustainable than trying to reconstruct an entire month in one sitting.
What the rating and long availability tell me
The app’s 3.2 average is neither a strong endorsement nor evidence that it is unusable. With around twenty-three thousand ratings and roughly two thousand eight hundred reviews, there is enough public feedback to treat the experience as varied. I would read recent comments with a narrow focus: look for remarks about the current version, data recovery, reminders, editing, and purchase expectations rather than relying on a single enthusiastic or frustrated review.
Its long availability and broad install base show that Expense IQ has remained relevant to a substantial audience, but age can cut both ways. A mature app may have a familiar workflow and years of practical refinement. It may also feel less modern than newer finance tools, especially if those competitors emphasize automation, bank connections, or cleaner onboarding.
The minimum operating requirement is Android 4.4, which makes the app accessible to older devices. That can be useful if you are trying to avoid replacing a phone just to run a budgeting tool. Still, compatibility does not guarantee that every current device behaves identically, so I would test notifications and backup-related actions on the phone you actually plan to use.
Expense IQ compared with spreadsheets, banking apps, and newer trackers
Compared with a spreadsheet, Expense IQ is quicker for routine entries and more naturally focused on personal spending. A spreadsheet offers greater freedom: you can design formulas, add custom columns, and keep a fully portable file. If you enjoy building your own system or need unusual financial calculations, a spreadsheet may remain the better choice. Expense IQ wins when you want less setup and a more purpose-built daily habit.
Compared with a bank’s own app, the main difference is independence. A banking app is usually the place to verify balances and transactions at the source. Expense IQ is better suited to adding context, planning future spending, and combining information into a personal budget. I would use the bank statement as the authority and the money manager as the organizing layer, rather than assuming the two records will always match automatically.
Compared with newer budgeting apps, Expense IQ may appeal to users who prefer direct entry and a straightforward personal ledger. A competitor that automatically imports transactions could save time, but automation can also introduce categorization errors or require more account access than some people want. The right choice depends on whether your priority is minimal typing or maximum control over what enters the system.
That comparison also explains who should skip it. If you want investment tracking, detailed accounting, automatic synchronization across financial institutions, or a highly visual coaching program, I would look elsewhere before committing your routine to this app. If you simply want to understand everyday expenses and remember bills, its focused scope may be an advantage rather than a weakness.
Questions I would settle before making it my main money tool
Would I use it for a family budget? Yes, if the household agrees on categories and everyone follows the same entry routine. I would first clarify who can view the records, how access is protected, and how the data would be recovered if the main phone were lost. Shared money tracking fails more often from unclear responsibility than from a missing feature.
Can it replace checking my bank account? No. I would still verify balances and completed payments through the financial institution. A manually maintained record is excellent for planning, but it can lag behind reality if a transaction is forgotten, reversed, duplicated, or posted under a different amount.
Is paying for an in-app purchase automatically worthwhile? Not for me without testing the free workflow first. Since individual purchases can range from a few dollars to well over one hundred dollars, I would read the exact description and renewal terms shown at the point of purchase. I would pay only for a capability I had already identified as useful, not because a locked option appeared tempting.
Will it suit someone who dislikes bookkeeping? Probably not. The app can make the process more organized, but it cannot remove the need to enter or review information if your chosen workflow is manual. A person who repeatedly abandons spreadsheets and notebooks may also abandon this unless reminders and a very small category system make the habit manageable.
Is it appropriate for private or professional financial records? I would use restraint. For personal budgeting, it can be a practical organizer. For sensitive business accounts, shared finances with legal complexity, or records that must be preserved formally, I would use a dedicated accounting or document system alongside it and keep independent copies.
My cautious recommendation
Expense IQ Money Manager is a reasonable choice for Android users who want a free starting point for expense tracking, budget planning, and bill reminders without immediately handing their routine over to an automated financial service. I like the deliberate nature of manual recording, especially for someone trying to understand habits rather than merely watch balances change.
My recommendation comes with conditions. Keep categories simple, review entries regularly, avoid unnecessary personal notes, inspect notification and access settings, and confirm how your records can be preserved before you depend on the app. Treat the bank as the source for actual balances, and treat this app as a planning and reflection tool.
The mixed rating keeps me from calling it a universal winner, and the possible cost of optional purchases means the payment screens deserve attention. Even so, for a person who values control over automation and is willing to maintain the record, Expense IQ can earn a place in a practical monthly routine. For someone seeking seamless synchronization, advanced financial analysis, or formal accounting safeguards, choosing a different tool would be the more honest recommendation.
In short, I would suggest trying it with a small, low-risk sample of expenses first. If the entry process feels natural, the controls are clear on your device, and the reminders help rather than annoy you, it may become a useful money companion. If those basics feel uncertain, no amount of extra planning features will make it the right home for your financial history.
It is rated Everyone, so its intended audience is broad, and the app’s accessible operating requirement may help people using older Android phones. That does not remove the need for personal caution: the most important feature is your ability to understand and control the information you choose to record.
Gallery
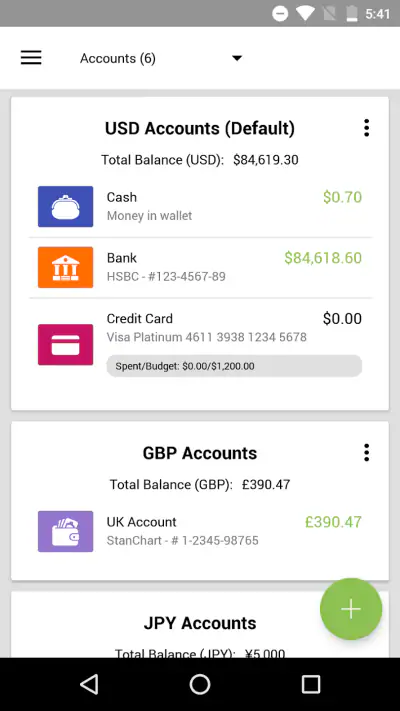
Expense IQ Money Manager Pros and Cons
- Clear charts make spending patterns easy to understand.
- Supports recurring transactions for regular bills and income.
- Useful budget categories help organize everyday expenses.
- Backup and restore options help protect your financial records.
- Multiple account support keeps cash
- bank
- and credit balances together.
- Some advanced features may require a premium upgrade.
- Manual transaction entry can feel slow for frequent purchases.
- The interface may seem dated compared with newer finance apps.
- Sync options and availability can vary by device or account setup.
- No financial app can guarantee complete protection if your device is compromised.
Expense IQ Money Manager Frequently Asked Questions
What is Expense IQ Money Manager used for?
Expense IQ Money Manager is a personal finance app designed to help you organize income, expenses, bills, budgets, and savings goals in one place. After reviewing its main tools, I found it particularly useful for users who want a clearer view of daily spending. Transactions can be categorized, searched, and reviewed through summaries and reports, making it easier to identify habits and manage household finances.
Does Expense IQ Money Manager support budgets and recurring bills?
Yes, the app includes tools for creating spending budgets and tracking recurring financial commitments. You can set limits for categories such as food, transportation, shopping, or entertainment, then compare actual spending with your planned amounts. Recurring transactions and bill reminders are also helpful for regular payments. However, users should still verify entries and reminders periodically rather than relying on the app as their only payment-management system.
Can I synchronize Expense IQ Money Manager across devices?
Expense IQ Money Manager may offer synchronization or backup options depending on the version, platform, and account configuration available on your device. Before switching phones or using the app on multiple devices, check its current synchronization and backup settings carefully. I recommend confirming that your latest data has been backed up and understanding whether synchronization is automatic, manual, cloud-based, or limited to certain editions.
Is Expense IQ Money Manager safe for storing financial information?
The application is intended for managing personal financial records, but users should remember that it may contain sensitive information about spending, accounts, and bills. Use a strong device passcode, enable any available app lock or security feature, and avoid entering unnecessary banking credentials. Also review the app’s current privacy policy and permissions before use, because security and data-handling practices can change with updates.
Is Expense IQ Money Manager free to download and use?
Expense IQ Money Manager can generally be downloaded at no initial cost, but some features may depend on premium access, in-app purchases, advertising, or the specific version offered for Android or iOS. Before relying on advanced reports, synchronization, export tools, or additional account features, review the store listing and purchase terms. Availability and pricing can vary by country, platform, and current developer offers.














